6 Smart Ways to Track Expenses Across Multiple Currencies
Jun 02, 2026


Dealing with paychecks that arrive from various countries often brings a unique set of challenges. Switching between time zones, invoicing in euros today and dollars tomorrow, and navigating constant changes in exchange rates can quickly become overwhelming. Staying organized and maintaining control of your finances requires more than just good intentions. This guide explains how to set practical financial goals, create a reliable budget, understand different tax regulations, and minimize risks. With these steps, you can simplify your financial management and dedicate more energy to the work you enjoy, without unnecessary stress about your international income.
You’ll see real-world examples of people sending funds to multiple accounts, using apps to monitor currency moves, and customizing expatriate tax filings. By the end, you’ll have a step-by-step path for smoothing out your income streams and boosting your savings without losing sleep over bookkeeping.
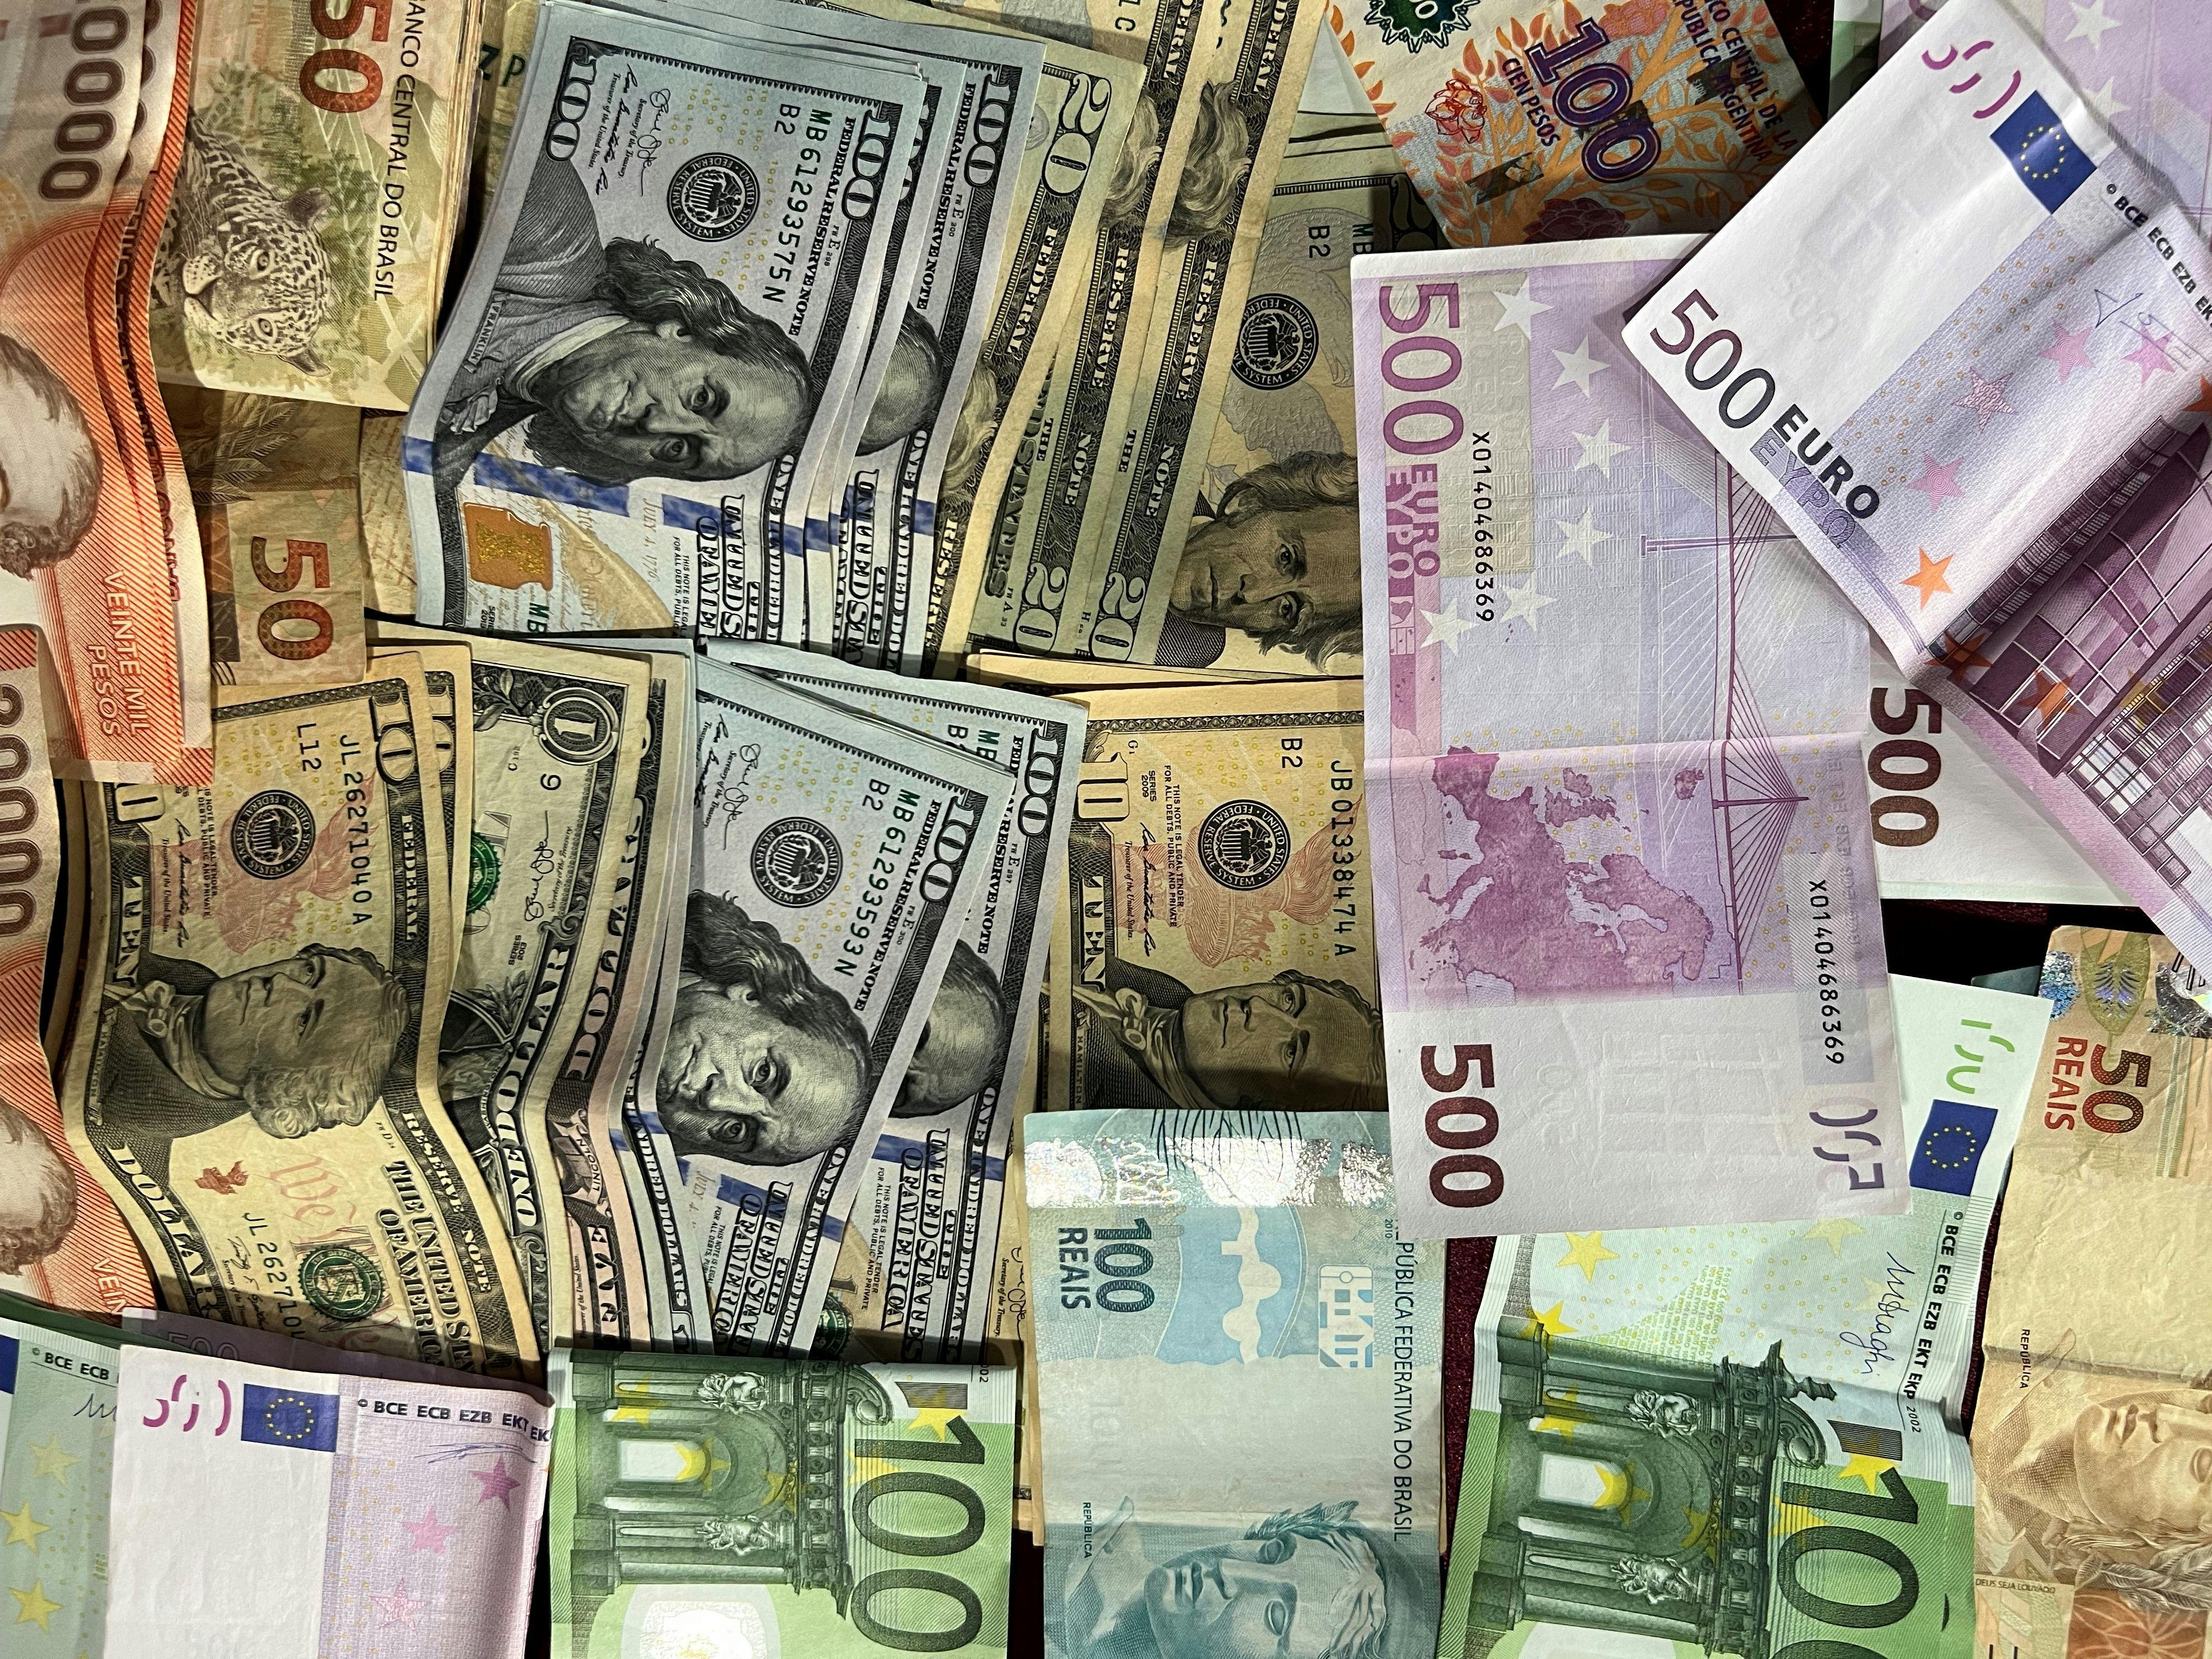
You might receive freelance fees in yen, royalties in pounds, or consulting rates in pesos. Each payment arrives on its own schedule, in its own currency. Tracking these inflows requires a system that records transaction dates, fees, and rates side by side. Start by listing every income channel in a simple spreadsheet, noting platform fees and transfer delays.
Consider the story of a designer who splits work between three clients in Tokyo, London, and São Paulo. She sets up subaccounts in her bank for each currency. When her London client pays, she directs the funds into her pound subaccount. This avoids constant conversions and allows her to transfer funds when the rate is favorable. It’s a small change that saved hundreds in fees last year.
First, identify what you’re saving for: a buffer worth three months of total expenses, a down payment on a home, or a sabbatical fund. Break each target into monthly milestones. For example, if you need $12,000 in a year, aim for $1,000 per month from your net income after fees and taxes.
Next, decide how each income stream contributes. You might direct checks from one country into an emergency fund, while payments from another fill your retirement account. This division keeps you motivated and prevents you from dipping into the same pool for varied goals.
Group your expenses by currency. List local rent, utilities, and food costs in the native denomination. Then track international bills—software subscriptions or overseas vendors—in dollars or euros. This split ensures you know exactly how much you owe in each currency.
Convert your monthly costs into a single base currency at the start of each month. Use mid-market rates from a service like Wise for consistency. If rent in Mexico costs 10,000 pesos, convert that figure today so you understand its dollar equivalent. Update your budget at month’s end to capture real rates and adjust the next cycle.
Filing taxes across borders pairs complexity with opportunity. First, track every payment and expense by date, amount, and country. Categorize receipts for desk supplies, home office costs, and travel meals. Many tax codes allow deductions on a pro-rata basis when you maintain clear logs.
Take the case of a translator who lives in Spain but works for clients in Canada and Australia. She hires a local accountant to file nonresident returns in those countries, then uses credits in her Spanish tax form to avoid double taxation. That move slashed her overall bill by 15%.
Each tool adds one layer of clarity. Collectively, they create a digital dashboard that shows your cash position in every market at a glance.
These steps protect your funds and allow you to sleep well, no matter where your work takes you.
Having a clear budget, smart accounts, and good records helps you control your income. Set specific goals and follow practical steps to organize your cash flow. This approach transforms irregular payments into a reliable financial foundation.
Managing multiple income streams often turns confusing without an organized approach. A unified platform gathers information from payment centers, expense records, and...
Jul 10, 2026
Keeping track of royalties and licensing income often becomes overwhelming with contracts, sales reports, and payments arriving from various countries at unpredictable...
Aug 19, 2026
Creating a fully online business involves several important legal steps that help establish a solid foundation. Choosing the right business structure is essential, as it...
Aug 09, 2026
Remote teams often deal with disjointed apps and tedious manual handoffs, which can delay projects and lead to missed deadlines. Bringing everything together becomes...
Jun 15, 2026
Teams working remotely often manage a mix of time zones, various digital tools, and dispersed workspaces, which can make the hiring process feel challenging and slow....
Jun 24, 2026
Successful project funding across international borders calls for thoughtful planning and persistence. Grants and microloans offer valuable resources that can help bring...
Jul 05, 2026
Building a company without a central office calls for new ways of working together. Teams located in different time zones rely on well-defined goals, dependable...
Jun 28, 2026
Building a franchise without relying on a central office involves creating processes that work seamlessly in a variety of environments, such as homes, co-working...
May 27, 2026
Managing funding applications demands careful handling of sensitive documents, strict attention to deadlines, and thorough compliance checks. Disorganized workflows...
Jun 06, 2026
Many support teams encounter difficulties as users work across various platforms and operate in different time zones. Automated tools address these challenges by...
Aug 22, 2026
Working from different cities calls for dependable ways to exchange files and keep information safe. Cloud platforms make it possible for people to collaborate from...
Jun 21, 2026
Teams unlock their creativity and communicate more clearly when they use a user-friendly whiteboarding solution. Clunky tools that lag or don’t work with other apps...
Aug 30, 2026
People rely on cloud storage to keep files accessible and up to date on any device. Whether working from a home office or catching up at a local café, users can open,...
Jul 21, 2026
Working across different time zones often makes collaboration more challenging. Meetings scheduled for one group might fall during another’s nighttime hours, leaving...
Sep 04, 2026